Texas · Auto insurance
Is a Flooded Car Covered by Insurance in Texas?
Flood damage to a car is handled by one specific coverage, and neither a home policy nor a flood policy steps in if you do not have it. Here is what pays, how a total loss is decided and what to do in the first hours.

In short
A flooded car is covered in Texas if you carry comprehensive coverage on your auto policy. The Texas Department of Insurance says comprehensive pays for flood damage, minus your deductible. Liability-only policies do not cover it, and neither do homeowners policies or National Flood Insurance Program policies. If repairs cost about as much as the car is worth, the company will treat it as a total loss and pay its value.
- Comprehensive coverage is the only part of a standard auto policy that pays for flood damage to your car.
- Homeowners insurance and National Flood Insurance Program policies do not cover cars.
- A car can be totaled even if water never reached the engine, because modern electronics are costly to repair.
- Have a mechanic look at a flooded car before you try to start it.
- A flood-totaled car in Texas gets a salvage or nonrepairable title marked “Flood Damage.”
In this article
- Which coverage pays when a car floods?
- Does home insurance or flood insurance cover a car?
- How does the insurance company decide if a flooded car is totaled?
- What does a flood claim actually pay? A worked example
- What should you do in the first 24 hours?
- What happens to the title of a flood-totaled car?
- Will the claim cover a rental car, towing or your deductible?
- How can you get ready before the next storm?
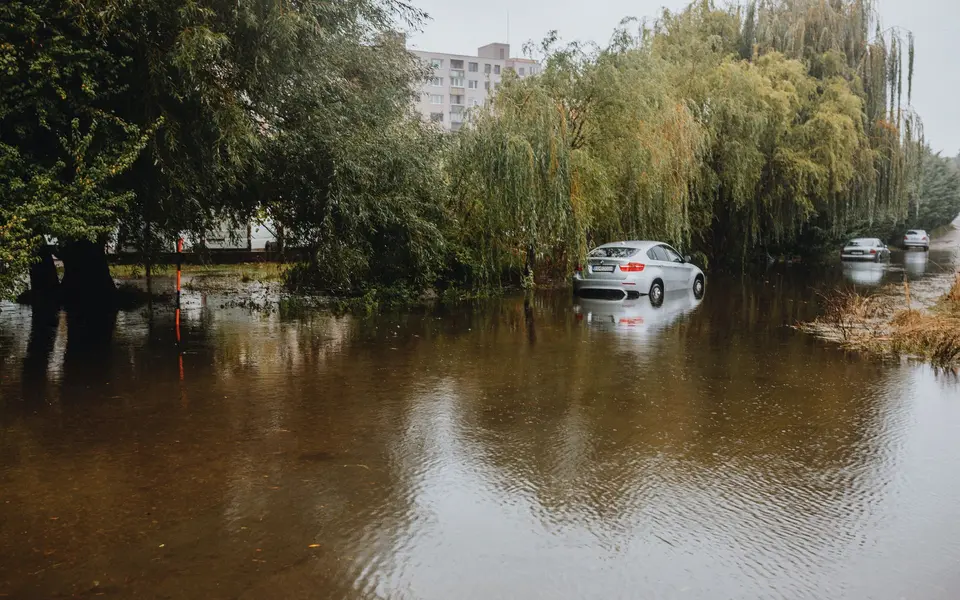
A spring storm stalls over North Texas, the street fills faster than the drains can clear it, and the water reaches the door sills of your car. Whether insurance pays comes down to one line on your policy: comprehensive coverage. If it is there, flood damage is covered, minus your deductible. If it is not, no other policy you own is likely to pay.
Which coverage pays when a car floods?
The Texas Department of Insurance answers this directly: if you have comprehensive auto coverage, you are covered for flood damage to your car. Comprehensive is the part of a policy that pays for damage from causes other than a crash, such as hail, fire, theft, vandalism and flood. Our guide to comprehensive and collision coverage explains how the two differ.
It does not matter whether the water came from a creek out of its banks, a flooded underpass or a parking garage that filled during a storm. What matters is whether comprehensive is listed on your declarations page for that vehicle.
Comprehensive is optional under Texas law. The state requires only liability coverage. If you have a car loan or lease, though, the Texas Department of Insurance notes that your lender will require both collision and comprehensive. Drivers with paid-off cars are the ones most likely to have dropped it. If you are weighing that choice, see full coverage vs. liability-only in Texas.
Does home insurance or flood insurance cover a car?
No, and this surprises many people after a storm.
Which policy pays for what after a flood
| Policy you may have | Flood damage to your car | Why |
|---|---|---|
| Auto policy with comprehensive | Covered, minus your deductible | Flood is a cause comprehensive pays for |
| Auto policy, liability only | Not covered | Liability pays other people, not your own car |
| Auto policy with collision but no comprehensive | Not covered | Collision pays for crashes, not rising water |
| Homeowners or renters policy | Not covered | These policies exclude flood and are not written for vehicles |
| National Flood Insurance Program policy | Not covered | FEMA excludes most self-propelled vehicles such as cars |
What this means for you: a flood policy on your house and an auto policy on your car do two different jobs. If you live or park in a low spot, you may need both. Our article on whether you need flood insurance in Texas covers the house, and your home insurance review is a good time to check both.
How does the insurance company decide if a flooded car is totaled?
The company compares two numbers: what the car was worth right before the flood, called its actual cash value, and what it would cost to repair. The Texas Department of Insurance says that if repairs cost about as much as or more than the car is worth, the company will likely total it. Actual cash value and other claim terms are defined in our insurance glossary.
The department also warns that the old rule of thumb, that a car is totaled only when water reaches the dashboard, no longer fully holds. Newer cars carry more electronics, and those are expensive to repair. A car can be totaled even if water never reached the engine.
If the car is totaled, the payment is its actual cash value minus your deductible, not the price of a new one. The department suggests these steps if you think the offer is low:
- Get quotes from used car dealers for a similar vehicle.
- Check online prices and local ads for the same year, model and mileage.
- Document special features or custom parts.
- Ask the company which source it used to set the value.
The full process, including appraisal, is in how a total loss claim works in Texas.
What does a flood claim actually pay? A worked example
The numbers below are round figures chosen to show the math. They are not a quote or a prediction for any real car.
Maria parks her sedan at an apartment complex in Garland. Overnight, water rises to the bottom of the seats. Her car was worth $18,000 before the storm. She owes $20,000 on the loan and carries comprehensive with a $1,000 deductible.
The shop estimates $17,500 to replace the wiring, carpet, seats and control modules. Repairs are about equal to the value, so the company totals the car.
Maria’s claim in numbers (example)
| Item | Amount |
|---|---|
| Actual cash value before the flood | $18,000 |
| Comprehensive deductible | $1,000 |
| Insurance payment | $17,000 |
| Loan balance | $20,000 |
| Still owed to the lender after the payment | $3,000 |
What this means for you: the payment goes toward the loan first, and Maria still owes $3,000 on a car she no longer has. The Texas Department of Insurance says a gap policy pays the difference between your loan balance and the settlement, and that without one you are responsible for the rest. See whether you need gap insurance in Texas if you owe more than your car is worth.
Now change one fact. If Maria had dropped comprehensive to save money, the payment would be $0 and she would still owe the full $20,000.
What should you do in the first 24 hours?
The Texas Department of Insurance recommends a short list of actions, and the order matters.
- Stay out of moving water. The National Weather Service says 12 inches of rushing water can carry away most cars and 2 feet can carry away SUVs and trucks. No car is worth wading for.
- Do not start the engine. The department says experts recommend having a mechanic look at a flooded car before you try to start it, to avoid more damage.
- Take photos and video. Capture the damage and the waterline inside and out. If it is safe, photograph the car while it is still in the water.
- Call your agent or insurance company as soon as you can. Your policy and insurance card list a number for reporting claims.
- Do not dry it out yourself if water got inside. The department says improper drying can lead to mold and electrical problems, so this is a job for a professional.
- Keep damaged items until the adjuster has seen them.
- Find your title. If you cannot, the Texas Department of Motor Vehicles can issue a replacement by mail or in person, and you will need it if the car is totaled.
If the car floated away, the department suggests contacting the police department’s unclaimed autos unit to see whether it has been recovered.
Be patient but keep notes. After a large storm an adjuster may take time to reach you, and the department notes that the usual claim deadlines can be extended for disasters. The Texas Department of Insurance Help Line is 800-252-3439 if you cannot find your company’s number.
What happens to the title of a flood-totaled car?
A car that is totaled does not keep a clean title. According to the Texas Department of Motor Vehicles, a vehicle damaged by fresh water, salt water or a flood of unknown origin carries the Texas brand “Flood Damage.” The Texas Department of Insurance adds that a vehicle declared a total loss must be retitled as salvage or nonrepairable.
This matters in two situations.
If you keep the car. The Texas Department of Insurance says the company will subtract the salvage value from your payment, and that after repairs you must get a new title from the Texas Department of Motor Vehicles before driving it. A car with a salvage history can be harder to sell and harder to insure later.
If you are buying a used car after a big storm. Flooded cars are sometimes cleaned up and resold. The Texas Department of Motor Vehicles suggests looking for water stains under the carpet, rust on screws inside the console, dried mud under the dashboard and a musty smell, and running the vehicle identification number through its Title Check before you buy. It also says these checks will not catch every case, so have a mechanic inspect the car.
Will the claim cover a rental car, towing or your deductible?
Each of these depends on coverage you chose before the storm.
- Deductible. Your comprehensive deductible is subtracted from the payment whether the car is repaired or totaled. The trade-offs are in how to choose a car insurance deductible.
- Towing. Towing and labor coverage, if you bought it, pays up to its dollar limit to tow a car that cannot be driven.
- Rental car. Rental reimbursement coverage pays a set daily amount up to your policy’s limit while your car is being repaired after a covered loss. Policies differ on which losses qualify, so check yours before you rent.
- Hail in the same storm. Hail dents and broken glass are comprehensive losses too. See how hail damage claims work and how windshield claims work.
One more protection: the Texas Department of Insurance says a company cannot refuse to renew your auto policy because of weather damage.
How can you get ready before the next storm?
You cannot add coverage for damage that has already happened, so the useful work is done on a dry day.
- Look at your declarations page and confirm comprehensive is listed for every car you could not afford to replace.
- Know your deductible and keep that amount within reach.
- If you owe more than the car is worth, ask about gap coverage.
- Learn the low spots on your commute and where you park. Dallas–Fort Worth underpasses and creek crossings can fill quickly in a heavy storm.
- Keep photos of your car and a copy of your title somewhere other than the glove box.
If your current policy lacks comprehensive and the price is the reason, compare options before dropping protection. Our guide on how to switch car insurance companies shows how to do that without a gap.
How Assured Insurance Group helps
Assured Insurance Group helps drivers in Flower Mound, Plano, Garland and across Dallas–Fort Worth with auto insurance. We will walk through your current policy with you, show you whether comprehensive is on each vehicle and go over your options. You can call, email [email protected] or visit an office, including our Garland location. To review your car insurance before storm season, request a quote or call 214-222-5234.
Questions people ask next
Does liability-only insurance cover a flooded car in Texas?
No. Liability coverage pays for damage and injuries you cause to other people. Flood damage to your own car is paid only by comprehensive coverage. If you financed the car, your lender most likely required comprehensive and collision, so check your declarations page. If the car is paid off and you dropped comprehensive, the loss is yours.
Does flood insurance on my house cover my car?
No. FEMA lists most self-propelled vehicles such as cars, including their parts, among the things a National Flood Insurance Program policy does not cover. Homeowners policies also exclude flood. The car needs its own comprehensive coverage on an auto policy.
Will my insurance company drop me for a flood claim?
The Texas Department of Insurance says a company cannot refuse to renew an auto policy because of weather damage. That protects you from losing the policy over a storm claim. It does not promise that your price stays the same, since rates in an area can change after widespread losses.
Can I keep my car if the insurance company totals it for flood damage?
Usually, yes. The Texas Department of Insurance says to tell the company as soon as possible that you want to keep it. The company will subtract the car’s salvage value from your payment, and the car may get a salvage title. After repairs you must get a new title from the Texas Department of Motor Vehicles before driving it.
How fast does the insurance company have to pay a flood claim on a car?
Texas law sets deadlines: a company must acknowledge a claim within 15 days, accept or reject it within 15 business days after it has the information it needs, and pay within 5 business days after agreeing to pay. The Texas Department of Insurance notes that these deadlines can be extended after a disaster.
Does comprehensive coverage pay for things that were inside the flooded car?
Comprehensive coverage is written for the vehicle itself. Personal items such as a laptop, tools or a stroller are generally a question for your homeowners or renters policy, and most of those policies exclude flood. Check both policies, list what was lost and ask before assuming either one will pay.
Sources and further reading
- Texas Department of Insurance: Flooded cars, what to know about insurance claims and repairs
- Texas Department of Insurance: Automobile insurance guide
- Texas Department of Insurance: My car was totaled. Now what?
- Texas Department of Motor Vehicles: Water damage and title brands
- FEMA National Flood Insurance Program: What flood insurance covers and does not cover
- National Weather Service: Turn Around Don’t Drown
General information for Texas readers, current as of August 2026. It is not legal, tax or insurance advice. Your coverage depends on the wording of your own policy.
More auto insurance guides
- How to Switch Car Insurance Companies Without a Gap in Coverage
- What Car Insurance Is Required in Texas? The 30/60/25 Rule Explained
- How Much Car Insurance Do You Really Need in Texas?
- Full Coverage vs. Liability-Only Car Insurance in Texas: Which Fits Your Car?
- Is Uninsured Motorist Coverage Worth It in Texas?
- PIP vs. Medical Payments Coverage in Texas: What Is the Difference?