Texas · Life insurance
The Life Insurance Medical Exam: What to Expect and How to Prepare
The exam is shorter and simpler than most people fear. Knowing what is measured, what else the company checks and how to prepare takes most of the worry out of it.

In short
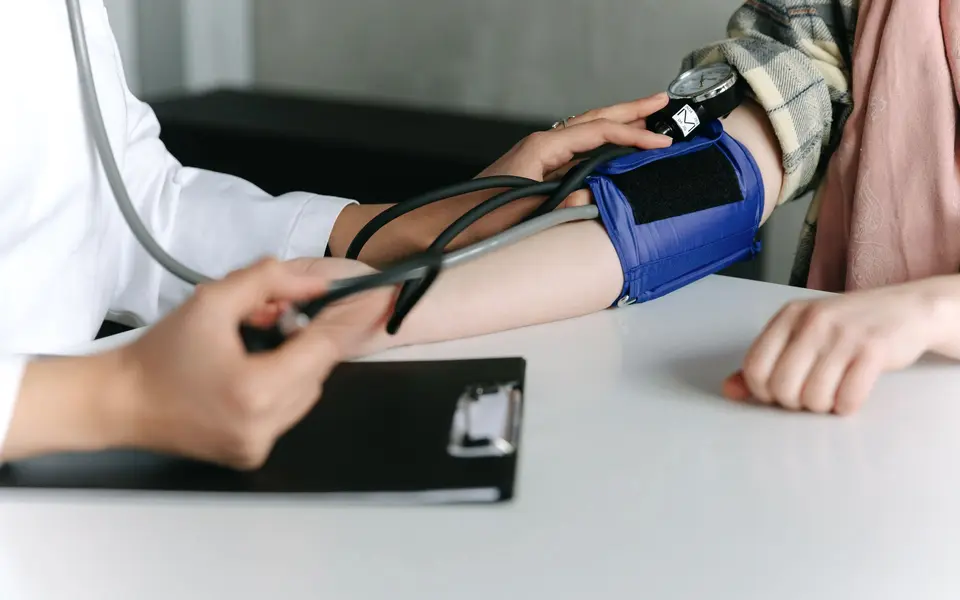
A life insurance medical exam is a short health check arranged by the insurance company. An examiner reviews your health history, records your height, weight, blood pressure and pulse, and collects blood and urine samples. The company combines the results with other records to decide whether to offer a policy and at what price. Rest, follow the examiner's instructions and answer every question honestly.
- The exam covers health questions, basic measurements and blood and urine samples.
- The company also looks at outside records, which can include prescription history, motor vehicle records and the MIB.
- Honest answers matter most: Texas life policies have a two-year contestable period during which a claim can be denied over wrong or missing information.
- You can request your MIB file free once every 12 months and correct errors before you apply.
- A disappointing result is not the end: you can ask for the reason, compare other options and look at coverage that does not use an exam.
In this article
- What happens during a life insurance medical exam?
- How should you prepare for the exam?
- What else does the insurance company check besides the exam?
- What happens if you leave something off the application?
- How do the results affect what you pay?
- What if the results are worse than you expected?
- Can you skip the exam altogether?
If you applied for life insurance and were told an examiner will contact you, expect a short appointment: health questions, a few measurements, and blood and urine samples. The results help the company decide whether to offer you a policy and what to charge. The most useful preparation is a good night's sleep and honest answers.
What happens during a life insurance medical exam?
Insurance companies use a process called underwriting to decide whether to sell you a policy. The Texas Department of Insurance (TDI) says this often includes passing a medical exam and answering questions about your health, job and habits.
The National Association of Insurance Commissioners (NAIC) describes traditional underwriting as collecting extensive medical information, including a physical exam and fluids such as blood, urine and saliva. In practice the appointment has a few standard parts.
The usual parts of the exam
| Part of the exam | What the examiner does | What it tells the company |
|---|---|---|
| Health history | Asks about conditions, medications, surgeries, family history and your doctors | Whether your answers match your application and records |
| Measurements | Records height, weight, blood pressure and pulse | Basic signs of heart and metabolic health |
| Blood sample | Draws blood for lab work | Markers such as cholesterol and blood sugar, and other health indicators |
| Urine sample | Collects a sample for lab work | Kidney function and signs of nicotine or drug use |
| Extra tests, if asked | May include an EKG or more questions | Requested more often for older applicants or larger amounts |
What this means for you: nothing here is unusual if you have had a routine physical. The exam is not pass or fail in one reading. It is one set of facts the company weighs with everything else it knows.
The examiner is a medical professional hired by the insurer, not your own doctor, and does not decide your application. Many companies let you choose where the exam takes place, such as your home or workplace.
How should you prepare for the exam?
You cannot change your health in a week, but you can avoid a reading that makes you look less healthy than you are. Use this checklist:
- Schedule it for a time you are rested. Many people choose early morning, before the day's stress and meals.
- Follow the fasting instructions you are given. The examiner or the company will tell you whether to fast and for how long. Their instructions control.
- Drink water. It makes the blood draw and the urine sample easier.
- Go easy the day before. Skip alcohol, a heavy salty meal and a hard workout, all of which can affect readings.
- Ask about caffeine and nicotine. Both can raise blood pressure for a short time. Follow what the examiner tells you.
- Take your regular medications unless your own doctor says otherwise, and bring a list with doses.
- Gather your details. Names and addresses of your doctors, dates of surgeries and diagnoses, and a photo ID.
- Wear short sleeves or sleeves that roll up.
If you are sick on the day, ask to reschedule. A fever or a rough night can show up in the numbers.
If your first blood pressure reading runs high because you are nervous, say so and ask whether the examiner can take it again after a few minutes of sitting quietly.
What else does the insurance company check besides the exam?
The exam is only part of the file. The Office of Public Insurance Counsel notes that you will usually answer health questions and may also have to provide medical records or answer questions about your finances.
Companies also draw on outside records. The NAIC lists prescription drug history, motor vehicle records, credit reports and the Medical Information Bureau (MIB) among the external sources insurers use. So a string of speeding tickets on US-75 can matter to a life insurance application, not only to your auto insurance.
The MIB deserves a moment. The Consumer Financial Protection Bureau describes it as a company that collects information about medical conditions and hazardous hobbies, used by life and health insurers when you apply for individual coverage, and shared only with your permission. You can request one free copy of your file every 12 months. If you have applied for individual life or health coverage before, it is worth checking before you apply again.
The insurance glossary defines underwriting and the other terms you will see on the application.
What happens if you leave something off the application?
This is the part of the process that can cost your family the most, so it deserves plain language.
TDI explains that Texas life policies have a two-year contestable period. If you die during that time, the company may review the information you gave on your application. If it learns you gave wrong information or did not disclose something, it can deny payment. TDI adds that this can happen even if the wrong information had nothing to do with the cause of death or was given by mistake. If the company denies payment, it must return the premiums to your beneficiary.
The Texas Insurance Code sets the outer limits. A policy must become incontestable after it has been in force for two years during the insured's lifetime, except for nonpayment of premiums. The code also says a misrepresentation in a life insurance application does not defeat recovery unless it concerns a material fact and affects the risks the company assumed. Whether a particular answer was material is a legal question, and a family in that position should talk with an attorney.
A worked example
Here is an example with round numbers. It is an illustration, not a prediction of how any claim would be decided.
A Garland father applies for a $500,000 term policy. On the application he answers no to a question about treatment for high blood pressure, although he has taken medication for it for three years. He feels fine and assumes it will not matter. The policy is issued.
Fourteen months later he dies in a car accident. Because the death falls inside the two-year contestable period, the company reviews the application and his medical and prescription records. It finds the medication history.
The company may deny the $500,000 claim on the ground that the answer was wrong and mattered to its decision, and return the premiums paid instead. His family is left to dispute that decision, at the worst possible time, over a question he could have answered truthfully. Had he disclosed the condition, he might have paid more or been offered different terms, and the claim would have rested on a clean application.
The lesson is simple. Tell the company everything it asks about, and let it decide what matters. How claims are reviewed and paid is covered in filing a life insurance claim in Texas.
How do the results affect what you pay?
TDI says companies consider your age, health, job and tobacco and alcohol use when they set prices. After underwriting, the company places you in a rate class. The names vary by company, but the pattern is similar.
How underwriting results are usually grouped
| Result | What it generally means | What you can do |
|---|---|---|
| Best classes | Health, build and history meet the company's top standards | Accept, and check the offer against your needs |
| Standard class | Average health for your age | Ask what kept you out of a better class |
| Rated or substandard | A health condition or other risk raises the price | Compare other options, and ask whether the rating can be reviewed later |
| Postponed | The company wants to wait, for example after a recent procedure | Ask when you can reapply |
| Declined | The company will not offer this policy | Ask for the reason and look at other types of coverage |
What this means for you: the price quoted before the exam is an estimate. The offer after underwriting is the real one, and you are free to compare it or decline it.
Remember that TDI says Texas policies come with a free-look period of at least 10 to 20 days. If the policy that arrives is not what you expected, you can cancel in that window for a full refund.
What if the results are worse than you expected?
Start by asking the company for the specific reason and for a copy of your lab results. Sometimes the cause is a one-off reading. Sometimes the exam finds something you should take to your doctor, which is valuable in itself.
Then look at your options:
- If the issue is a known condition, read about getting life insurance with a health condition. Companies treat the same diagnosis differently.
- If the offer is higher than planned, consider a smaller amount or shorter term now. The method in how much life insurance you need shows which needs to cover first.
- If you were declined, ask about coverage that does not rely on an exam, such as group coverage at work or the policies described in no-exam life insurance.
- If you are older, the choices change. See life insurance after 60.
Can you skip the exam altogether?
Sometimes. The NAIC explains that some insurers now use accelerated underwriting, which relies on outside data instead of a physical exam and can shorten the process from weeks to hours for applicants who qualify. Other policies are designed with no exam from the start, generally at a higher price.
There are trade-offs in price, amount and who qualifies, and those are the subject of no-exam life insurance. For many healthy applicants, taking the exam is still the way to get the best price on a larger life insurance policy. If you are choosing between policy types before you apply, the comparison of term and whole life insurance is the place to start.
How Assured Insurance Group helps
Assured Insurance Group helps people in Flower Mound, Plano, Garland and across Dallas–Fort Worth with life insurance. We will walk through your current policy and your options with you, including what to expect from the application and exam for the coverage you are considering. You can visit our Garland office or email [email protected] with questions before you apply. To get started, request a quote or call 214-222-5234.
Questions people ask next
Who pays for the life insurance medical exam?
The insurance company normally arranges the exam as part of its underwriting and does not bill the applicant for it. Confirm this when you apply, since each company sets its own process. If a company asks you to pay a fee for an exam before it will consider your application, ask for the reason in writing before you agree.
Can I get a copy of my life insurance exam results?
Ask for them when you apply or at the exam. Many companies will send your lab results to you or to your doctor on request. They are worth having, because the blood and urine work can flag something you did not know about. Share anything unexpected with your own doctor.
Can I be turned down for life insurance because of the exam?
Yes. The Texas Department of Insurance explains that underwriting decides whether a company will sell you a policy, and a company can decline you for health or other risk reasons. A decline from one company is not a decline from all. Companies weigh the same condition differently, so compare options before you give up.
Does the exam check for drugs and nicotine?
Expect the lab work to look for signs of tobacco or nicotine use and drug use, along with general health markers. Companies consider tobacco and alcohol use when they set prices, according to the Texas Department of Insurance. Answer the application questions about these honestly, since the lab results are compared with what you wrote.
Do I need a new medical exam to renew or convert a term policy?
Often not. The Texas Department of Insurance explains that convertibility lets you exchange a term policy for permanent coverage without a medical exam, and renewability lets you extend the term without one. Both depend on the wording of your policy, so check your contract. Reinstating a policy that lapsed can require health questions or a new exam.
What if I disagree with something in my medical records?
Start with the source. Ask your doctor's office to correct an error in your chart. For your MIB file, the Consumer Financial Protection Bureau says you can request one free report every 12 months, and you can dispute information you believe is wrong. Fixing records before you apply is easier than explaining them afterward.
Sources and further reading
- Texas Department of Insurance: Life insurance guide
- Office of Public Insurance Counsel: Life insurance shopping guide
- National Association of Insurance Commissioners: Accelerated underwriting
- Consumer Financial Protection Bureau: MIB, Inc.
- Texas Insurance Code, Chapter 705: Misrepresentations by policyholders
- Texas Insurance Code, Chapter 1101: Life insurance policy provisions
General information for Texas readers, current as of November 2026. It is not legal, tax or insurance advice. Your coverage depends on the wording of your own policy.
More life insurance guides
- Naming a Life Insurance Beneficiary: Mistakes That Delay or Derail a Payout
- Is a Life Insurance Payout Taxable?
- Life Insurance for Business Owners: Key Person Coverage and Buy-Sell Funding
- Is Life Insurance Through Work Enough?
- Converting Term Life Insurance to Permanent Coverage: When It Makes Sense
- Universal Life Insurance Explained: Flexible Premiums and Their Risks