Texas · Commercial insurance
Business Interruption Insurance: How It Replaces Income After a Loss
What has to happen before it pays, which bills it covers, how long the payments last and how to pick a limit that matches your real numbers.

In short
Business interruption insurance, also called business income coverage, replaces the net income your business would have earned and pays continuing expenses such as rent, payroll, loan payments and taxes while you are closed for repairs. It pays only when a covered cause of loss, such as fire or wind, physically damages your property. It is usually part of a property policy or a business owner’s policy.
- It pays lost net income plus continuing bills such as rent, loan payments, taxes and payroll during the period of restoration.
- The trigger is direct physical damage from a cause your property policy covers. If the cause is excluded, such as flood, the lost income is not covered either.
- The Insurance Information Institute notes a typical waiting period of 48 to 72 hours before payments begin.
- Extra expense coverage pays the added cost of operating from a temporary location or with rented equipment.
- The limit should come from your own financial records, because the claim is proven with those same records.
In this article
- What does business interruption insurance pay for?
- What has to happen before it pays?
- When do the payments start, and how long do they last?
- What is extra expense coverage?
- What if the damage happens somewhere else?
- What does business interruption insurance not cover?
- How do you choose a limit?
- How is it sold, and what affects the price?
Service: Commercial Insurance in Flower Mound, Plano and Garland
Property insurance pays to fix the building and replace the equipment. It does not pay your rent, your payroll or your own income during the months the doors are closed. Business interruption insurance is the coverage that does, and it pays only when covered physical damage is the reason you had to stop.
What does business interruption insurance pay for?
The NAIC defines business interruption as loss of income as a result of property damage to a business facility. The coverage is built to put the business where it would have been if the loss had not happened: the same net income, with the fixed bills paid.
The Insurance Information Institute (Triple-I) lists the main things it helps with during the period of restoration.
What business income coverage typically pays
| What it pays | Plain meaning | How it is proven |
|---|---|---|
| Lost net income | The profit you would have earned if you had stayed open | Tax returns, profit and loss statements, sales records |
| Rent, mortgage or lease payments | The location cost that continues while you are closed | Lease or loan statements |
| Loan payments | Equipment and business loans that still come due | Loan documents |
| Taxes | Taxes that still must be paid during the shutdown | Tax records |
| Employee payroll | Wages for staff you keep so you can reopen | Payroll reports |
What this means for you: the claim is measured from your financial records. Income that is not on the books cannot be replaced, so clean monthly records are part of your coverage.
This coverage pays for the time you lose. The damaged property itself is paid under the property part of the policy, which is explained in our article on what commercial property insurance covers.
What has to happen before it pays?
Three things have to line up on most policies.
- Direct physical damage. Something physical must be damaged or destroyed at the insured location, such as a fire in the kitchen or a roof torn open by wind.
- A covered cause of loss. The cause has to be one your property form covers. Triple-I puts it plainly: business income coverage applies only to events covered by the core property policy.
- A necessary suspension. You must have had to stop or slow your operations because of that damage.
The second point matters most in Texas. The Texas Department of Insurance (TDI) notes that most commercial property policies do not cover flooding. If a flash flood closes your shop for six weeks and flood is excluded, the lost income is excluded too. A National Flood Insurance Program policy will not help with that part, because its commercial coverage excludes financial losses caused by business interruption. Our article on whether you need flood insurance in Texas explains the building and contents side.
A slow month, road construction outside your door, a supplier that raises prices or a customer who leaves are business risks, not insured losses. There is no physical damage from a covered cause, so the coverage does not respond.
When do the payments start, and how long do they last?
Two time rules control every business income claim.
The waiting period. Most policies do not pay from the first hour. Triple-I notes there is typically a 48 to 72-hour waiting period before the period of restoration begins. It works like a deductible measured in time. A two-day closure after a small loss may fall entirely inside it.
The period of restoration. This is the length of time the policy helps pay lost income and extra expenses while the business is being restored. It generally runs until the property should reasonably be repaired, rebuilt or replaced, not until your sales are back to where they were.
That last point catches owners off guard. Customers do not all return the day you reopen. Some policies add extra time after reopening, and Triple-I notes that the period can be extended by endorsement, to as long as 360 days. Ask which time limits apply on your policy and whether they fit how long a rebuild would really take in Dallas–Fort Worth, where contractors are stretched after every large hailstorm.
What is extra expense coverage?
Extra expense pays costs above your normal operating expenses that you take on to keep the business running or to reopen sooner. TDI describes it as coverage for the added costs to return to normal after damage.
Triple-I gives these examples:
- Renting a temporary location while the original one is repaired
- Replacing hardware, technology and furniture so you can work
- Paying overtime or hiring extra staff
- Leasing equipment
For some businesses, extra expense matters more than lost income. An accounting office, a clinic or a dispatch center cannot afford to go dark, so the goal is to move and keep operating. A restaurant or a manufacturer usually cannot move quickly, so lost income is the bigger number. Our guide to restaurant insurance in Texas covers that situation in more detail.
What if the damage happens somewhere else?
The basic coverage is about damage at your own premises. Picture a fire on the ground floor that closes the whole building for a month but does no damage inside your suite upstairs. Your own property was not damaged, so the basic coverage may not pay your lost income. Several extensions exist for losses that start elsewhere.
Extensions for losses that begin off your premises
| Extension | When it applies | Limits to know |
|---|---|---|
| Civil authority | A government order blocks access to your premises because of physical damage to a nearby property you do not own | Triple-I notes coverage typically does not exceed two consecutive weeks, and the policy may still require a direct physical loss |
| Contingent business interruption (dependent properties) | Damage at a business you depend on cuts your earnings: a supplier, a buyer of your goods, a manufacturer of your product, or a “leader” location such as an anchor store that draws your customers | The damage must still come from a covered cause of loss |
| Utility services | Your operations stop because electric, gas or water service is interrupted | Sold as an endorsement, usually with a time limit or until service is restored |
What this means for you: none of these is automatic on every policy, and each has its own limit. If one supplier, one big customer or one anchor tenant could shut down your revenue, ask to see the dependent property wording.
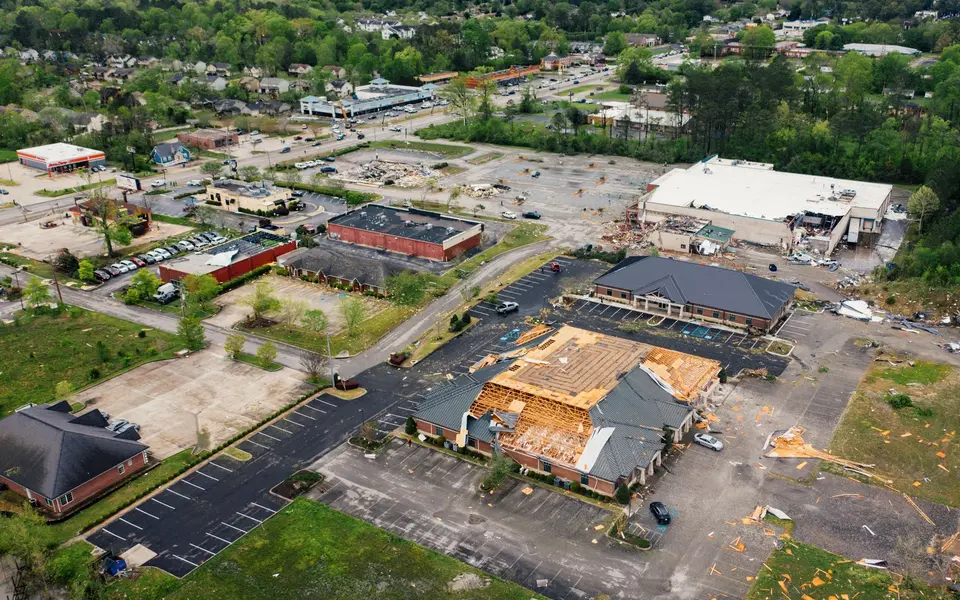
A tornado that crosses a shopping center in Garland is a good test. The stores that were hit have direct damage. The stores next door may be undamaged but blocked off by the city for a week. Those neighbors are relying on civil authority coverage, not on the basic business income coverage. For how the property side of a storm claim works, see our article on tornado damage in North Texas, written for homeowners but built on the same policy logic.
What does business interruption insurance not cover?
Triple-I lists these as outside the coverage:
- Broken items from the covered loss. Damaged glass, equipment and stock are paid under the property coverage, not the income coverage.
- Flood and earthquake damage. These need a separate policy.
- Undocumented income. Anything that is not in your financial records.
- Utilities. A utility outage by itself, unless you added the endorsement.
- Pandemics, viruses and communicable diseases.
Two more limits follow from how the coverage works. A cyber attack that locks your systems usually involves no physical damage, so lost income from it belongs under a different policy, explained in our article on cyber liability insurance for a small business. And if the owner cannot work because of illness or death, that is a life and disability question. See life insurance for business owners and our life insurance page.
How do you choose a limit?
The limit, or the number of months, is your decision. Triple-I’s rule of thumb is to use gross earnings and projections to estimate future profits. If the loss costs more than the limit you chose, you pay the rest yourself.
Work through it in this order.
- Take last year’s profit and loss statement and find monthly net income. Use the busy season if your sales are seasonal.
- List the expenses that would continue while you are closed: rent, loan payments, insurance, taxes, and the payroll you would keep.
- Add the two. That is the monthly amount you need replaced.
- Estimate how long a full rebuild would take, including permits, contractor delays and re-ordering equipment. Be realistic.
- Multiply the monthly amount by the number of months.
- Add a figure for extra expense if you would rent temporary space or equipment.
- Compare the result with the limit and time period on your policy.
A worked example
This is an illustration with round numbers, not a quote. A bakery in Plano earns $10,000 a month in net income and has $15,000 a month in bills that would continue during a shutdown: rent, an oven loan and the wages of two key employees. A fire closes the kitchen for four months.
The business income loss is $25,000 a month for four months, or $100,000. The owner also rents a shared commercial kitchen for $3,000 a month to keep wholesale accounts alive, which is $12,000 in extra expense. The total need is about $112,000.
If the policy has a 72-hour waiting period, the first three days are not paid. If the limit was set at $50,000 years ago, the policy stops at $50,000 and the owner carries the other $62,000. If the period on the policy ends after 90 days, the fourth month is unpaid no matter what the dollar limit says.
How is it sold, and what affects the price?
Business income coverage is rarely a stand-alone purchase. Triple-I describes two common routes: inside a business owner’s policy, which bundles property, liability and business income for small to mid-sized businesses, or as an endorsement to a commercial property policy. Our guide to the business owner’s policy explains which businesses qualify, and what insurance a Texas small business needs puts it in order of priority.
Triple-I lists the factors that move the price: your industry, the number of employees, the amount of coverage, prior claims and your location. A restaurant, with a higher fire risk, may pay more than a real estate office. The definition of each term on your quote is in our insurance glossary, and the wider picture is on our commercial insurance page.
If your lease has rules about how long you have to rebuild or whether rent stops after a fire, read them next to this coverage. Our article on insurance requirements in a commercial lease shows where to look.
How Assured Insurance Group helps
Assured Insurance Group helps business owners in Flower Mound, Plano, Garland and across Dallas–Fort Worth with commercial insurance, including business income and extra expense coverage. We will walk through your current policy with you and go over your options, including the waiting period and the limit. You can visit our Plano office, email [email protected], or request a quote. You can also call us at 214-222-5234.
Questions people ask next
Is business interruption insurance the same as business income coverage?
Yes. Insurance companies and agents use both names for the same coverage, and some policies call it “business income and extra expense.” The declarations page of a property policy or business owner’s policy shows whether it is included, the limit or time period that applies, and any waiting period.
Does business interruption insurance cover a power outage?
Not by itself on most policies. A utility failure away from your premises is usually not covered unless you add a utility services endorsement. That endorsement extends business income or extra expense coverage to a shutdown caused by an interruption of electric, gas or water service, usually up to a time limit.
Did business interruption insurance pay for pandemic closures?
In most cases it did not. The Insurance Information Institute lists pandemics, viruses and communicable diseases among the things business income coverage does not pay for. The coverage is built around physical damage to property from a covered cause, and a government closure order with no damaged property does not meet that test on most policies.
Does it cover lost income after a flood?
Only if flood is a covered cause of loss on your policy, and on most commercial property policies it is not. The National Flood Insurance Program does not fill the gap: its commercial policies exclude financial losses caused by business interruption. Ask whether flood can be added to your property policy with business income included.
How long does business interruption insurance pay?
It pays during the period of restoration, which is the time it should reasonably take to repair or replace the damaged property. Policies set an outer limit in different ways: a dollar limit, a number of months, or both. Check which one your policy uses and whether an extension applies after you reopen.
Can I buy business interruption insurance by itself?
It is normally sold with property coverage, because it depends on a covered property loss. Small and mid-sized businesses usually get it inside a business owner’s policy. Others add it as an endorsement to a commercial property policy or include it in a commercial package policy.
Sources and further reading
- Insurance Information Institute: Do I need business interruption insurance?
- Insurance Information Institute: Property insurance for small businesses
- Texas Department of Insurance: Commercial property insurance guide
- FloodSmart (NFIP): The ins and outs of NFIP commercial coverage
- NAIC: Glossary of insurance terms (business interruption)
General information for Texas readers, current as of October 2026. It is not legal, tax or insurance advice. Your coverage depends on the wording of your own policy.
More commercial insurance guides
- What Is a Certificate of Insurance (COI), and How Do You Get One?
- Contractor Insurance in Texas: What General Contractors and Trades Are Asked to Carry
- Liquor Liability and the Texas Dram Shop Act: What Bars and Restaurants Risk
- Running a Business From Home in Texas: What Your Homeowners Policy Does Not Cover
- Hired and Non-Owned Auto Insurance: When Employees Drive Their Own Cars for Work
- Commercial Umbrella vs. Excess Liability: What Is the Difference?